Jim: sell & get paid instantly
CloudWalk
- 4.4
- 463.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
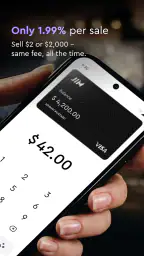
Jim: sell & get paid instantly Pros and Cons
Pros
- Instant payment options can help sellers access earnings quickly.
- Simple listing tools make it easy to post items for sale.
- Useful for local transactions and quick handoffs.
- In-app messaging helps buyers and sellers coordinate details.
- Supports selling unwanted items without creating a full online store.
Cons
- Payment availability may vary by country or supported payment method.
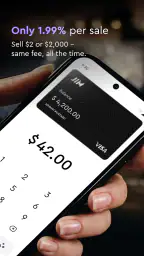
- Transaction fees can reduce the amount sellers ultimately receive.
- Some listings may attract low offers or unreliable buyers.
- Users may need to arrange shipping or meetups themselves.
- Account verification could be required before selling or withdrawing funds.
 Analysis by All-app
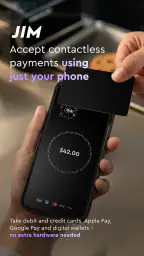
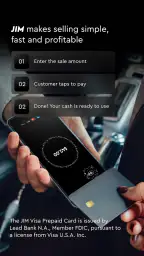
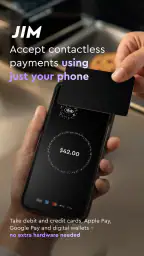
I approached Jim: sell & get paid instantly as a practical finance app rather than a full business-management platform. Its idea is straightforward: use a phone as a card reader when you need to accept a payment away from a traditional checkout. That makes the app interesting for independent sellers, mobile service providers, market-stall operators, and anyone who occasionally needs to take card payments without carrying dedicated equipment.
My first impression is that Jim is aimed at reducing the distance between a sale and a completed payment. The appeal is not a long list of accounting tools; it is the possibility of handling a transaction from the same device I already carry. That focus can be a real advantage when I am working at a customer’s home, moving between appointments, or selling in a place where a fixed counter makes little sense.
Jim is free to install, belongs to the Finance category, and is developed by CloudWalk. It is rated for Everyone, so its presentation is accessible rather than aimed at a specialist business audience. The app has an average rating of 4.4 from around 2.2 thousand ratings, with more than 100 thousand installs. Those figures suggest that it has attracted a meaningful early audience, although they should not be mistaken for proof that every phone, card, or selling situation will behave identically.
How Jim feels when a customer is waiting
The most important test for an app like this is not how attractive the opening screen looks. It is what happens when another person is standing in front of me, ready to pay, while I am trying to complete a sale without creating an awkward pause. Jim’s value depends on keeping that moment simple: open the payment flow, enter or confirm the amount, let the customer complete the card interaction, and check that the transaction has finished before moving on.
In that setting, perceived speed matters more than a collection of secondary features. A payment app can feel slow even when the phone itself is responsive if the process makes me revisit information, wait without clear feedback, or wonder whether I should try again. I would therefore treat the confirmation state as part of the product’s usefulness. Before handing over an item or ending a service visit, I would look for a clear indication that the payment has actually completed rather than relying on a vague animation or the customer’s assumption.
Jim’s phone-based approach is especially convenient for short, informal selling sessions. A craft seller at a weekend event, a tutor collecting payment after a lesson, or a technician finishing a small repair can keep the transaction close to the work instead of directing the customer toward a separate terminal. The trade-off is that the phone becomes part of the checkout experience, so its battery, connectivity, screen condition, and general readiness matter more than they would with a dedicated reader.
I would prepare the app before the first customer arrives. That means signing in, checking that the phone is charged, making sure the device is updated to a supported system, and becoming familiar with the payment screen. These are small steps, but they remove the worst kind of delay: discovering during a live sale that I still need to complete setup or understand an unfamiliar prompt.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
A realistic day-to-day example
Imagine I run a small mobile cleaning service and finish a job at a client’s home. I do not want to ask the client to find cash, and I do not want to carry a separate checkout device for a handful of appointments. Jim can fit naturally into that workflow because the phone is already with me. I can keep the payment moment at the end of the visit, confirm the amount with the customer, and avoid turning a simple collection into a separate administrative task.
That same convenience has a practical limit. If I am completing many transactions one after another, the phone is no longer merely a communication tool; it is now a busy point-of-sale device. I would give myself a repeatable routine: confirm the amount aloud, wait for the completed result, and record the sale immediately if I need a separate business log. This reduces mistakes caused by rushing from one customer to the next.
For occasional payments, Jim seems easier to justify than buying or carrying equipment that spends most of its time unused. For a busy shop with staff, inventory, refunds, receipts, and end-of-day reporting, I would compare it carefully with a dedicated point-of-sale system. A phone card reader can solve the payment-location problem, but it does not automatically solve every operational problem around a growing business.
What happens during heavier use
The app’s strongest case is mobility, but heavier use exposes the difference between a convenient payment tool and a complete checkout environment. During a busy market or a rush of appointments, I would care about more than whether one payment can be started. I would want a workflow that remains understandable when I am repeating it many times, handling interruptions, answering questions, and keeping track of which customer has already paid.
A useful habit is to separate payment confirmation from order fulfillment. I would not hand over a product simply because the customer has reached the final screen. I would first verify the completed status, then mark the item as sold or finish the service. This is a simple but important control when several transactions happen close together and a failed or abandoned attempt could otherwise be confused with a successful one.
Another non-obvious trade-off is screen availability. A phone used as a reader may be needed for calls, messages, navigation, photos, or business authentication at the same time. If a customer interrupts the payment flow with a call or notification, I would avoid assuming that the transaction failed. I would return to the app and check its status before trying again. Repeating a payment without checking can create confusion and may lead to duplicate attempts.
For a seller who works outdoors, the environment also matters. Bright sunlight can make a phone screen harder to read, while cold, rain, or a crowded counter can make handling the device less comfortable. These are not faults unique to Jim, but they are part of the real cost of replacing a conventional terminal with a phone. I would use a stable surface or a secure grip and keep the customer-facing part of the interaction visible whenever possible.
Stability is more than opening quickly
With a finance app, reliability means preserving clarity when something goes wrong. A payment can be interrupted by a weak connection, an incoming call, a locked screen, or a customer changing their mind. The safest response is not to repeat the transaction immediately. I would first inspect the app’s current state and, when necessary, verify the result through the available transaction record before taking another payment.
This recovery mindset is particularly important because payment errors are more serious than an ordinary app crash. If a social app closes, I can reopen it later. If a payment flow becomes unclear, both the seller and customer need to know whether money moved. Jim is therefore best used by someone willing to pause and verify rather than someone who expects every interruption to resolve silently.
I also recommend keeping a simple external sales record for a small business. That does not mean Jim is unsuitable; it means a payment tool should not be the only place where I remember what was sold, to whom, and for what amount. A notebook, spreadsheet, or existing bookkeeping process can provide a second reference if I need to reconcile a busy day. This is one of the most useful ways to protect against confusion without expecting the payment app to become an entire back office.
The app’s current version is 1.4.19, and it requires Android 7.0 or newer. I would check the phone before planning to use it as the only way to accept payments. A device that technically meets the minimum can still deliver a less comfortable experience if it is old, has a worn battery, struggles with multitasking, or has an unreliable connection. Minimum compatibility is a starting point, not a promise of identical performance on every supported handset.
Device limits I would consider first
Jim’s resource demands are easiest to judge in context. A payment app does not need to dominate the phone to be useful, but the phone must remain responsive during the transaction. On an older device with very little free storage or many background apps, I would close unnecessary tasks before a sales session. This is not a special trick for Jim; it is a sensible way to reduce interruptions when the phone is serving as a checkout.
Battery planning deserves equal attention. A seller who spends the whole day away from a desk should carry a power bank or arrange charging access, because a phone that dies cannot accept payments even if the app itself is functioning perfectly. The phone’s camera, calls, and navigation may already consume power, so I would not estimate readiness from the payment app alone.
Connectivity is another practical constraint. A mobile card-reader app depends on a communication path between the phone, the payment service, and the customer’s card interaction. I would test the intended selling location before relying on Jim there, especially in a basement, rural area, crowded venue, or building with inconsistent reception. If the connection is uncertain, I would prepare a backup payment method rather than discovering the problem with a queue waiting.
These constraints help define who should skip Jim. I would hesitate to recommend it as the sole checkout method for a high-volume store, a business that needs several employees working simultaneously, or a seller who cannot tolerate ambiguity during a connection failure. A conventional terminal or a more comprehensive point-of-sale package may be the better choice when operational controls matter more than portability.
Where it beats the usual alternatives
Compared with cash, Jim can be more convenient for customers who do not carry notes and coins, while the seller avoids preparing change. Compared with asking customers to make a transfer, a card-based flow can feel more like a normal purchase and may be easier to use at the moment of service. Compared with a dedicated reader, the phone approach can reduce the amount of equipment I need to carry for occasional or mobile work.
The comparison changes when I consider scale. Cash does not depend on a phone battery or mobile connection, although it creates its own problems with change, storage, and reconciliation. A dedicated terminal can feel more purpose-built and may be easier to keep at a counter all day. A full point-of-sale system can offer broader business controls, but it may also bring more setup and complexity than a solo seller wants.
Jim makes the most sense when the payment location changes frequently and the seller values a compact setup. It is less compelling if I already have a reliable terminal, need advanced stock management, or want a single system to coordinate staff, products, reporting, and customer records. The right question is not whether Jim replaces every alternative. It is whether turning the phone into the payment device removes a real obstacle in my particular workflow.
My performance verdict
After weighing the speed expectations, busy-use friction, recovery needs, and device constraints, I see Jim as a focused tool for mobile card acceptance rather than a universal business platform. Its free price makes experimentation easy, and its Everyone rating keeps the entry point approachable. CloudWalk has positioned it around a clear everyday need: accepting payment where the seller happens to be.
My recommendation is strongest for freelancers, independent service providers, casual sellers, and small operators who want to avoid carrying separate hardware. I would install it before a selling day, complete the setup in a calm moment, test the workflow, and keep a backup method available. I would also verify every completed transaction before delivering goods or closing a service visit.
The key strength is mobility, but the key responsibility is verification. Jim can make a phone-based checkout feel practical when the alternative is cash, a transfer, or unnecessary equipment. It should not be treated as magic protection against weak connectivity, low battery, interruptions, or business-record problems. Used with a simple routine and realistic expectations, it is a sensible finance app for people who sell away from a fixed counter.
For my own choice, I would pick Jim when portability and occasional card acceptance matter most. I would choose a dedicated terminal or fuller point-of-sale solution when sales are constant, multiple people need access, or reporting and inventory controls are central to the business. That distinction gives the app a clear place: not every checkout, but a useful one for sellers who need the checkout to travel with them.
Frequently Asked Questions
What is Jim: sell & get paid instantly?
Jim: sell & get paid instantly is a marketplace app designed to help users list items for sale, communicate with potential buyers, and manage transactions from a mobile device. It focuses on making local or direct selling more convenient, with tools for creating listings, adding photos and descriptions, responding to inquiries, and receiving payment through supported options. Availability and features may vary by country.
How do I sell an item using Jim?
To sell an item, you generally create a listing by uploading clear photos, entering a title, selecting a category, writing an accurate description, and setting a price. Before publishing, check the listing carefully for mistakes and include relevant details such as condition, size, brand, and location. Good photographs and honest information can help attract serious buyers and reduce unnecessary messages.
Do sellers really get paid instantly on Jim?
The phrase “get paid instantly” refers to the app’s supported payment process, but the exact timing can depend on the payment method, buyer confirmation, account verification, bank processing, and regional availability. Not every transaction will necessarily appear in your bank account immediately. Review the app’s current payment terms, fees, limits, and withdrawal requirements before completing a sale.
Is Jim safe to use when meeting buyers or accepting payments?
As with any marketplace, safety depends partly on how you use the service. Keep conversations and payments inside the platform whenever possible, avoid sharing unnecessary personal information, and be cautious of buyers who pressure you, send suspicious links, or request unusual payment arrangements. For local exchanges, choose a public meeting place, tell someone where you are going, and verify payment before handing over the item.
Does Jim charge fees, and what devices can use the app?
Jim may apply service, transaction, payment-processing, or withdrawal fees depending on the type of sale, payment method, and country. The amount and terms can change, so check the fee information shown before publishing an item or accepting an offer. The app is intended for supported Android and iOS devices, but compatibility, account requirements, and available features should be confirmed in the official app store listing.